To define money order in plain terms, a money order is a prepaid payment document that lets you pay a specific person or organisation a specific amount, without using cash, a personal cheque, or a bank account. You buy it by paying the face amount plus a small fee, the issuer guarantees payment up to that amount, and the recipient can cash it or deposit it, usually after showing identification. This guide will define money order clearly, explain how it works step by step, compare it with cheques, bank transfers, and cash, and cover costs, safety, limits, and common mistakes, so you can decide when a money order is a sensible choice and when another payment method would suit you better. To define money order clearly, remember its four features: prepayment, a named payee, a fixed amount, and an issuer guarantee.
Money orders have existed for well over a century, and they remain useful today for a simple reason: not everyone has a bank account, a card, or access to online banking, and not every payment suits an electronic transfer. A landlord, a government office, a school, a small business, or a family member may ask for a guaranteed payment that can be posted or handed over in person, with a paper trail for both sides. Understanding how to define money order, and how to use one safely, is therefore practical financial knowledge, even in an increasingly digital world. This article is educational only; it does not give personal financial advice, and for a large or unusual payment you should check the rules of the issuer and, if needed, speak to a qualified adviser. People who need to define money order for a landlord or office usually need the practical steps, not just theory.
Define Money Order: Definition and Key Features
When we define money order, the essential features are prepayment, a named payee, a fixed amount, and an issuer guarantee. Prepayment means the buyer pays before the document is issued, so the money order is not a promise to pay later from an account that might be empty; the funds are already held by the issuer. The payee is the person or organisation named on the document, and only that payee, or someone the payee properly endorses it to, should be able to cash it. The amount is printed on the document and cannot be changed without invalidating it, which protects both buyer and recipient against tampering. The issuer, which may be a post office, a bank, a credit union, or a licensed money-transfer company, guarantees payment up to the face value, subject to its terms and to the recipient meeting identification requirements. When you define money order to a first-time buyer, stress keeping the receipt until payment is confirmed.
A money order also creates a paper trail. The buyer usually receives a receipt or a stub with a serial number, the amount, the date, and the payee name, and should keep that receipt until the payment is confirmed as received and cashed. That receipt is important: if the money order is lost, stolen, or never arrives, the buyer can use the receipt and serial number to ask the issuer to trace it, stop payment, or issue a replacement, although fees and waiting periods usually apply. Never throw the receipt away before the recipient confirms payment, and never send the receipt with the money order itself, because the receipt is your proof of purchase and your route to help if something goes wrong. Guides that define money order often compare it with cheques, cash, and bank transfers to show its place.
Parts of a Money Order
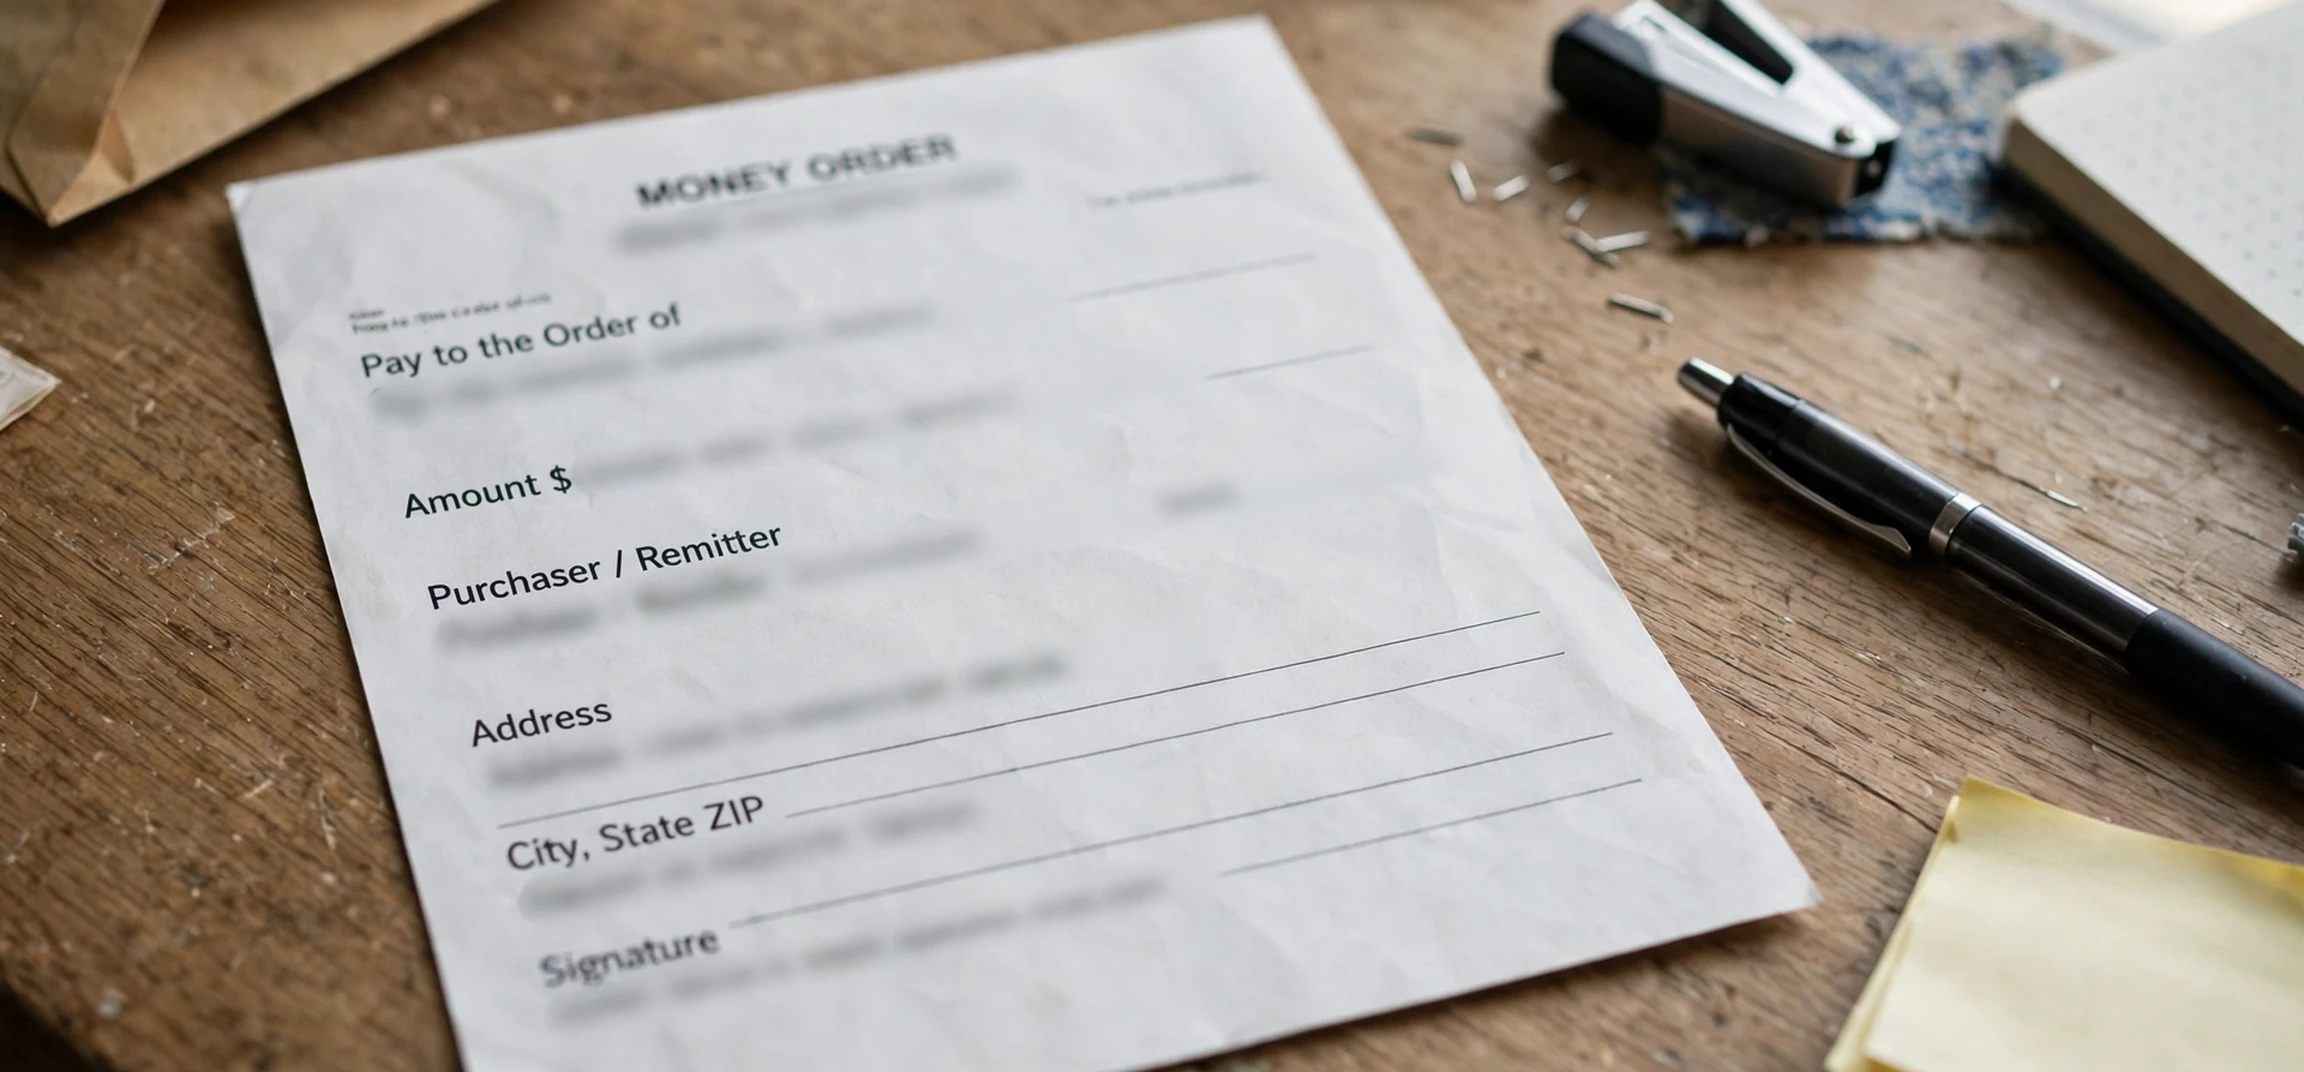
A typical money order has several fields, and filling them in correctly matters. The payee field names the recipient. The purchaser field names the buyer, and may ask for an address. The amount field shows the payment in figures and, on some forms, in words. The memo or note field lets you record what the payment is for, such as a month of rent or an account reference, which helps the recipient match the payment to your account. The signature field is where the buyer signs, and on some money orders the recipient also signs on the back when cashing it. Leave no field blank that should be completed, write clearly in ink, and never sign a blank money order or leave the payee field empty, because a blank money order is much easier for someone else to misuse if it is lost or stolen. To define money order safely, explain the scam in which a fake payment is followed by a request for a refund.
Define Money Order in Practice: How It Works Step by Step
Buying a money order is straightforward. First, decide the exact amount and the exact payee name, checking spelling against a bill, a lease, or an official notice, because a misspelled payee name can delay cashing. Second, go to an issuer, such as a post office, bank, or licensed agent, and tell the clerk the amount and payee. Third, pay the face amount plus the fee, in cash or by another method the issuer accepts; note that some issuers limit payment methods for larger amounts. Fourth, complete the money order carefully, sign it, and keep the receipt stub separate and safe. Fifth, deliver it to the recipient by hand or by tracked post if you are sending it by mail, and keep a note of the date, the serial number, and the tracking details. Anyone planning to define money order for family abroad should check international limits and fees first.
Cashing a money order is equally straightforward for the recipient. The payee takes the money order, plus photo identification, to a bank, a post office, or another cashing location accepted by the issuer. The cashing location checks the document for signs of alteration, verifies the amount and serial number where possible, and then pays the payee in cash or deposits the amount into the payee’s account, minus any cashing fee that location charges. Some locations set cashing limits, require an account, or refuse money orders from certain issuers, so the recipient should check in advance if the amount is large or the issuer is unfamiliar. If a money order cannot be cashed at one location, trying a bank where the recipient holds an account, or the issuing organisation itself, is often the next step. The receipt is central when you define money order, because it carries the serial number needed to trace payment.
Timing matters too. A money order does not usually expire quickly, but issuers may charge dormancy or service fees if it remains uncashed for a long time, and some recipients or organisations set their own deadlines for accepting payment. Send or deliver a money order promptly, tell the recipient it is on its way, and follow up if you have not had confirmation within a reasonable time. That follow-up is where the receipt proves its worth: with the serial number, the issuer can tell you whether the money order has been cashed, and if it has not, what options you have. To define money order in one sentence, call it a prepaid, guaranteed paper payment to a named payee.
Money Order Compared With Cheques, Cash, and Bank Transfers
To define money order fully, it helps to compare it with the alternatives. Cash is immediate and widely accepted, but it is risky to post, hard to trace if lost, and offers no proof of payment unless you obtain a separate receipt. A personal cheque draws on your bank account and can bounce if funds are insufficient, which is why some recipients, especially landlords and government offices, prefer a guaranteed payment instead. A bank transfer or electronic payment is fast and traceable, but it requires bank details on both sides and access to banking services, which not everyone has. A money order sits between these options: prepaid and guaranteed like a bank draft, paper-based like a cheque, and usable without a bank account like cash, but safer to send than cash because it is made out to a named payee. Cashing rules matter when you define money order, because locations set limits and identification requirements.
There are limits to that comparison. Money orders usually have maximum amounts per document, often around 1,000 in many systems, although limits vary by issuer and country, so a large payment may require several money orders, each with its own fee. Fees themselves vary: a post office money order may cost only a small amount, while a bank or convenience-store money order may cost more, and cashing fees can add further cost for the recipient. International money orders add exchange rates, additional fees, and longer delivery times, and they are less common now that electronic transfers and online payment services are widely available. For a large, urgent, or international payment, comparing total cost and delivery time across methods before you buy is always wise. Fees are part of any effort to define money order honestly, since buyer fees and cashing fees both apply.
| Payment Method | Needs a Bank Account | Guaranteed Funds | Traceable | Best For |
|---|---|---|---|---|
| Money order | No, for the buyer | Yes, prepaid by issuer | Yes, via serial number and receipt | Guaranteed paper payments without a bank account |
| Personal cheque | Yes | No, it can bounce | Yes, via bank statement | Payments where the recipient accepts cheques |
| Cash | No | Yes, if genuine | No, unless a receipt is given | Small in-person payments |
| Bank transfer | Yes, both sides usually | Yes, once sent | Yes, via bank records | Fast electronic payments between accounts |
| Bank draft | Usually, to buy one | Yes, bank guaranteed | Yes, via bank records | Large guaranteed payments |
The table is a general guide, not a set of rules for every country or issuer, because limits, fees, and acceptance vary. Always check the current terms of the issuer you plan to use, especially for amounts near a limit, for international payments, or for payments to a government office with strict acceptance rules. To define money order for rent payments, note the memo field, which helps a landlord match payment to an account.
Money Order Safety: Scams, Loss, and Common Mistakes
Money orders are safer than cash in many ways, but they are also a target for scams, and understanding those scams is part of learning how to define money order safely. A common scam involves a stranger sending you a money order or cheque for more than an agreed amount, then asking you to refund the difference before the original payment has cleared. The original document later proves to be fake, leaving you out of pocket for the refund. The protection is simple: never refund an overpayment until your bank confirms the original payment has fully cleared, never accept a money order from a stranger as part of a deal that requires you to send money onward, and be suspicious of any urgent request involving a money order, a courier, or a secret payment. Lost-payment help is easier to understand once you define money order through its serial number and receipt.
Other safety rules are practical. Buy money orders only from reputable issuers, never from an unknown seller. Fill in the payee name immediately, before the money order leaves your hands. Keep the receipt until payment is confirmed. If you post a money order, use tracked delivery and keep the tracking number. If a money order is lost or stolen, contact the issuer promptly with the receipt and serial number, and expect a waiting period while the issuer checks whether it has already been cashed. If you receive a money order and something feels wrong, such as a blurry print, an amount that looks altered, or pressure to cash it quickly and send money on, take it to your bank and ask staff to verify it before you act. Banks see fake money orders regularly and can often spot problems that are easy to miss. To define money order for someone without a bank account, highlight that buying one needs no account.
Common buyer mistakes include misspelling the payee name, writing the wrong amount, forgetting to sign, and losing the receipt. Most of these can be corrected only by buying a replacement or by going through the issuer’s cancellation process, which costs time and often a fee, so slow, careful completion at the counter is worth the extra minute. If you make a mistake, do not try to correct it with correction fluid or overwriting; ask the issuer what to do, because an altered money order may be refused when the recipient tries to cash it. Expiry and dormancy rules complete a full effort to define money order, even though most orders are used promptly.
For related everyday finance guides, see financial advisor meaning, arm loan meaning, and deductible meaning insurance. Those guides explain other terms you may meet alongside money orders, from professional advice to loan types and insurance costs, in the same plain-language style.
Frequently Asked Questions
How do you define money order in one sentence?
A money order is a prepaid, guaranteed payment document, bought for a specific amount plus a fee, made out to a named payee, who can cash it or deposit it with identification.
Do you need a bank account to buy a money order?
No. A buyer does not usually need a bank account to buy a money order, which is one of its main advantages. The recipient may find cashing easier with a bank account, but many post offices and cashing locations will also pay a payee with suitable identification.
What happens if a money order is lost?
Contact the issuer promptly with your receipt and serial number. The issuer can trace whether it has been cashed and, if it has not, may stop payment and issue a replacement, usually after a waiting period and a fee.
Do money orders expire?
Money orders do not usually expire quickly, but an uncashed money order may attract dormancy or service fees after a long period, depending on the issuer. Deliver and cash money orders promptly, and check the issuer’s terms for the exact rules.
Conclusion
To define money order simply: it is a prepaid, paper-based way to make a guaranteed payment to a named person or organisation, without needing a bank account or sending cash. Its strengths are prepayment, a named payee, a fixed amount, and a paper trail through the receipt and serial number. Its limits are fees, per-document maximums, cashing requirements, and the need for care against loss and scams. Used carefully, with the payee name checked, the receipt kept, and delivery tracked, a money order remains a reliable tool for rent, bills, fees, and payments where a guaranteed paper document is required. In a digital age, that old-fashioned reliability is exactly why it endures.



